What happens when AI agents and on-chain utilities take care of your shopping, transactions and payments?
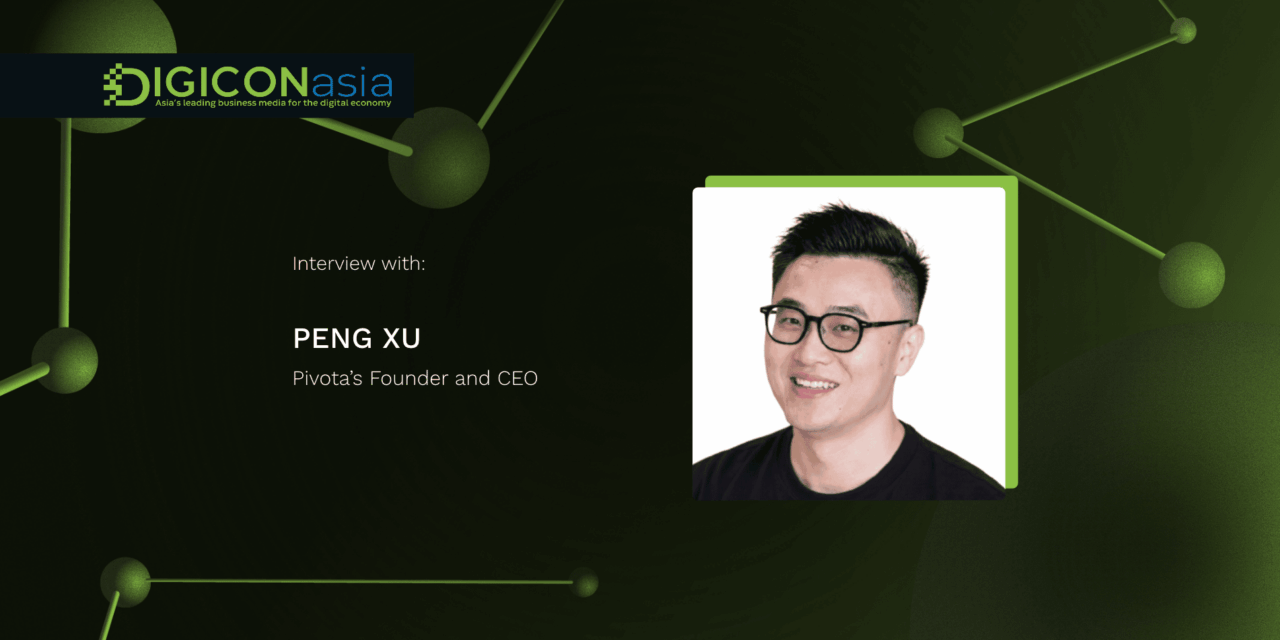
At the 2026 Cyberport Venture Capital Forum, I caught up with Peng Xu, Pivota’s Founder and CEO, who spoke in a fireside chat at the event’s Agentic Economy Summit on the topic “From AI agents to Agentic Commerce: Payments and On-Chain Utility in Everyday Life”.
One way for retailers and fintechs to leverage agentic AI for business value is through agentic commerce. But will agentic commerce take off in Asia Pacific?
According to Xu, agentic commerce is moving from AI that recommends products toward AI that can choose where to buy them and complete purchases on a user’s behalf. He sees that shift as an opportunity — but one that depends on solving trust, security, and checkout challenges.
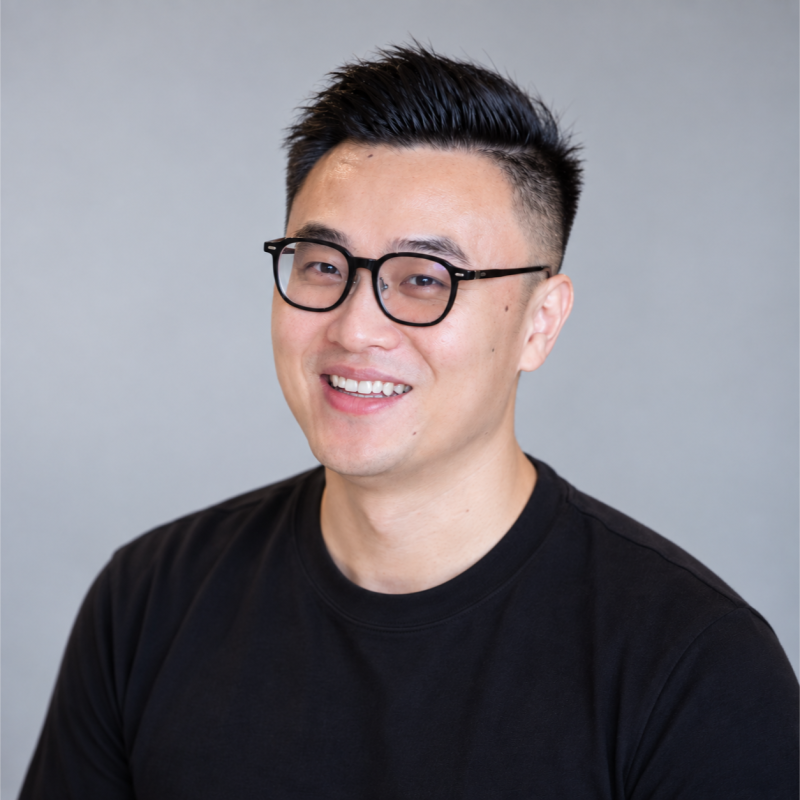
Peng Xu,Pivota’s Founder and CEO
From recommendations to completed purchases
“A good shopping experience is not just about finding relevant products; it is about helping customers act on that recommendation when they are ready to buy,” said Xu. “Pivota helps evaluate the relevant products, merchants and purchase channels based on factors such as availability, price and transaction feasibility.”
An agent may already suggest products, but finding a trustworthy merchant and completing the transaction are harder steps. As he put it: “When you choose a product, it’s so hard to find the right merchant.” Shoppers need to distinguish genuine sellers from fake storefronts, and compare prices, shipping, and reviews.
Pivota addresses this through two layers: merchant decisioning and auto execution. Merchant decisioning helps identify an appropriate, authentic seller, said Xu. Auto execution handles the operational work of buying — such as navigating checkout, providing shipping information, and completing payment.
He describes the company’s role as working “in between the AI agents and apps and the merchants” so an order can be completed and the result returned to the user.
This orchestration matters because the agent has to work with merchant storefronts and platforms, as well as payment providers and their authentication processes. Xu’s picture of the evolution is therefore not simply “AI picks an item”. It is an ecosystem in which agents, merchants, commerce platforms, and payment networks coordinate to complete a transaction.
To that end, Pivota recently signed an MOU together with Meitu’s EveLab Insight and Reap. Xu said: “We are exploring how that can make personalised beauty shopping more seamless, while leaving the customer in control of the purchase.”
The collaboration aims to enhance the shopping experience by connecting EveLab Insight’s personalised recommendations to Pivota’s product and merchant capabilities, then carrying the shopper’s choice through Reap’s payment infrastructure with their approval.
If deployed, consumers could discover products they might otherwise miss, while partners could gain a practical way to bring agentic commerce from recommendation to checkout.
Security and user trust are central
A recurring theme in the discussion was about balancing convenience and security for consumers. Xu agrees that agentic commerce introduces a new layer security concern: the agent may act before the consumer directly interacts with the merchant.
One risky approach is handing an agent a raw card number. Instead, he points to payment mechanisms in which card details stay with payment providers and the agent receives a limited-use token.
Blockchain, he said, could play a role in payment rails, alongside network tokens and stablecoins, for safer agent purchases using tokens tied to a specific order, merchant, and amount.
On-chain utility can help agentic commerce by making payments more programmable and easier to coordinate across parties — for example, enabling fast settlement or small, frequent payments, and potentially supporting spending rules for an agent.
He also describes mandates — where a consumer sets parameters such as a budget or recurring need — and confirms the proposed purchase or plan.
For Xu, the safeguards are not just a technical matter. Consumers must feel confident that the agent is acting in their interest, and merchants and payment providers must be willing to accept its transactions.
Growth across Asia
Xu expects agentic commerce to expand quickly as infrastructure improves. He said the US is currently an important market, while Asia is catching up, and predicted: “In the next six months, we’ll see a huge shift in Asia.”
He also expects the region’s growth to reflect its diversity: countries and markets use different wallets, funding sources, and payment systems. That variety makes the region more complex to serve than a single-market model, but Xu says activity is accelerating.
Mainland China, for instance, is different because commerce often happens within closed ecosystems. He points to shopping experiences tied to platforms such as Taobao and Douyin, where the platform can control more of the user journey. In Xu’s view, that can make it easier to build a smooth agent-assisted transaction than in a more open system involving many separate merchants and payment providers.
Xu also gave a personal example of ordering coffee through an assistant in Shanghai. The experience, he said, let him voice a request, select a product, and pay without jumping out to another app: “The purchase takes just 10 seconds to 15 seconds!”
For him, this illustrates how agentic commerce can make buying feel less like filling out a sequence of forms and more like giving simple instructions.
Adoption depends on reducing friction
Xu does not think adoption will be limited to younger, digitally native consumers. He argues that conversational interfaces may also help people who are less comfortable navigating apps, because they can state what they want and receive recommendations. But he agrees that people need time to trust an agent with purchases.
“A smooth experience, clear authorisation, and reliable payment safeguards are essential; too many obstacles can cause people to abandon the process,” he said.
Overall, Xu sees agentic commerce evolving from product discovery into delegated, authenticated purchasing. The technology is advancing, but its success will depend on trustworthy merchants, secure payment arrangements, integrations that complete orders reliably, and user experiences simple enough to earn confidence over time.


